Attacks on the East-West oil pipeline and other targets in Saudi Arabia will result in a larger-than-expected economic contraction in the kingdom this year.
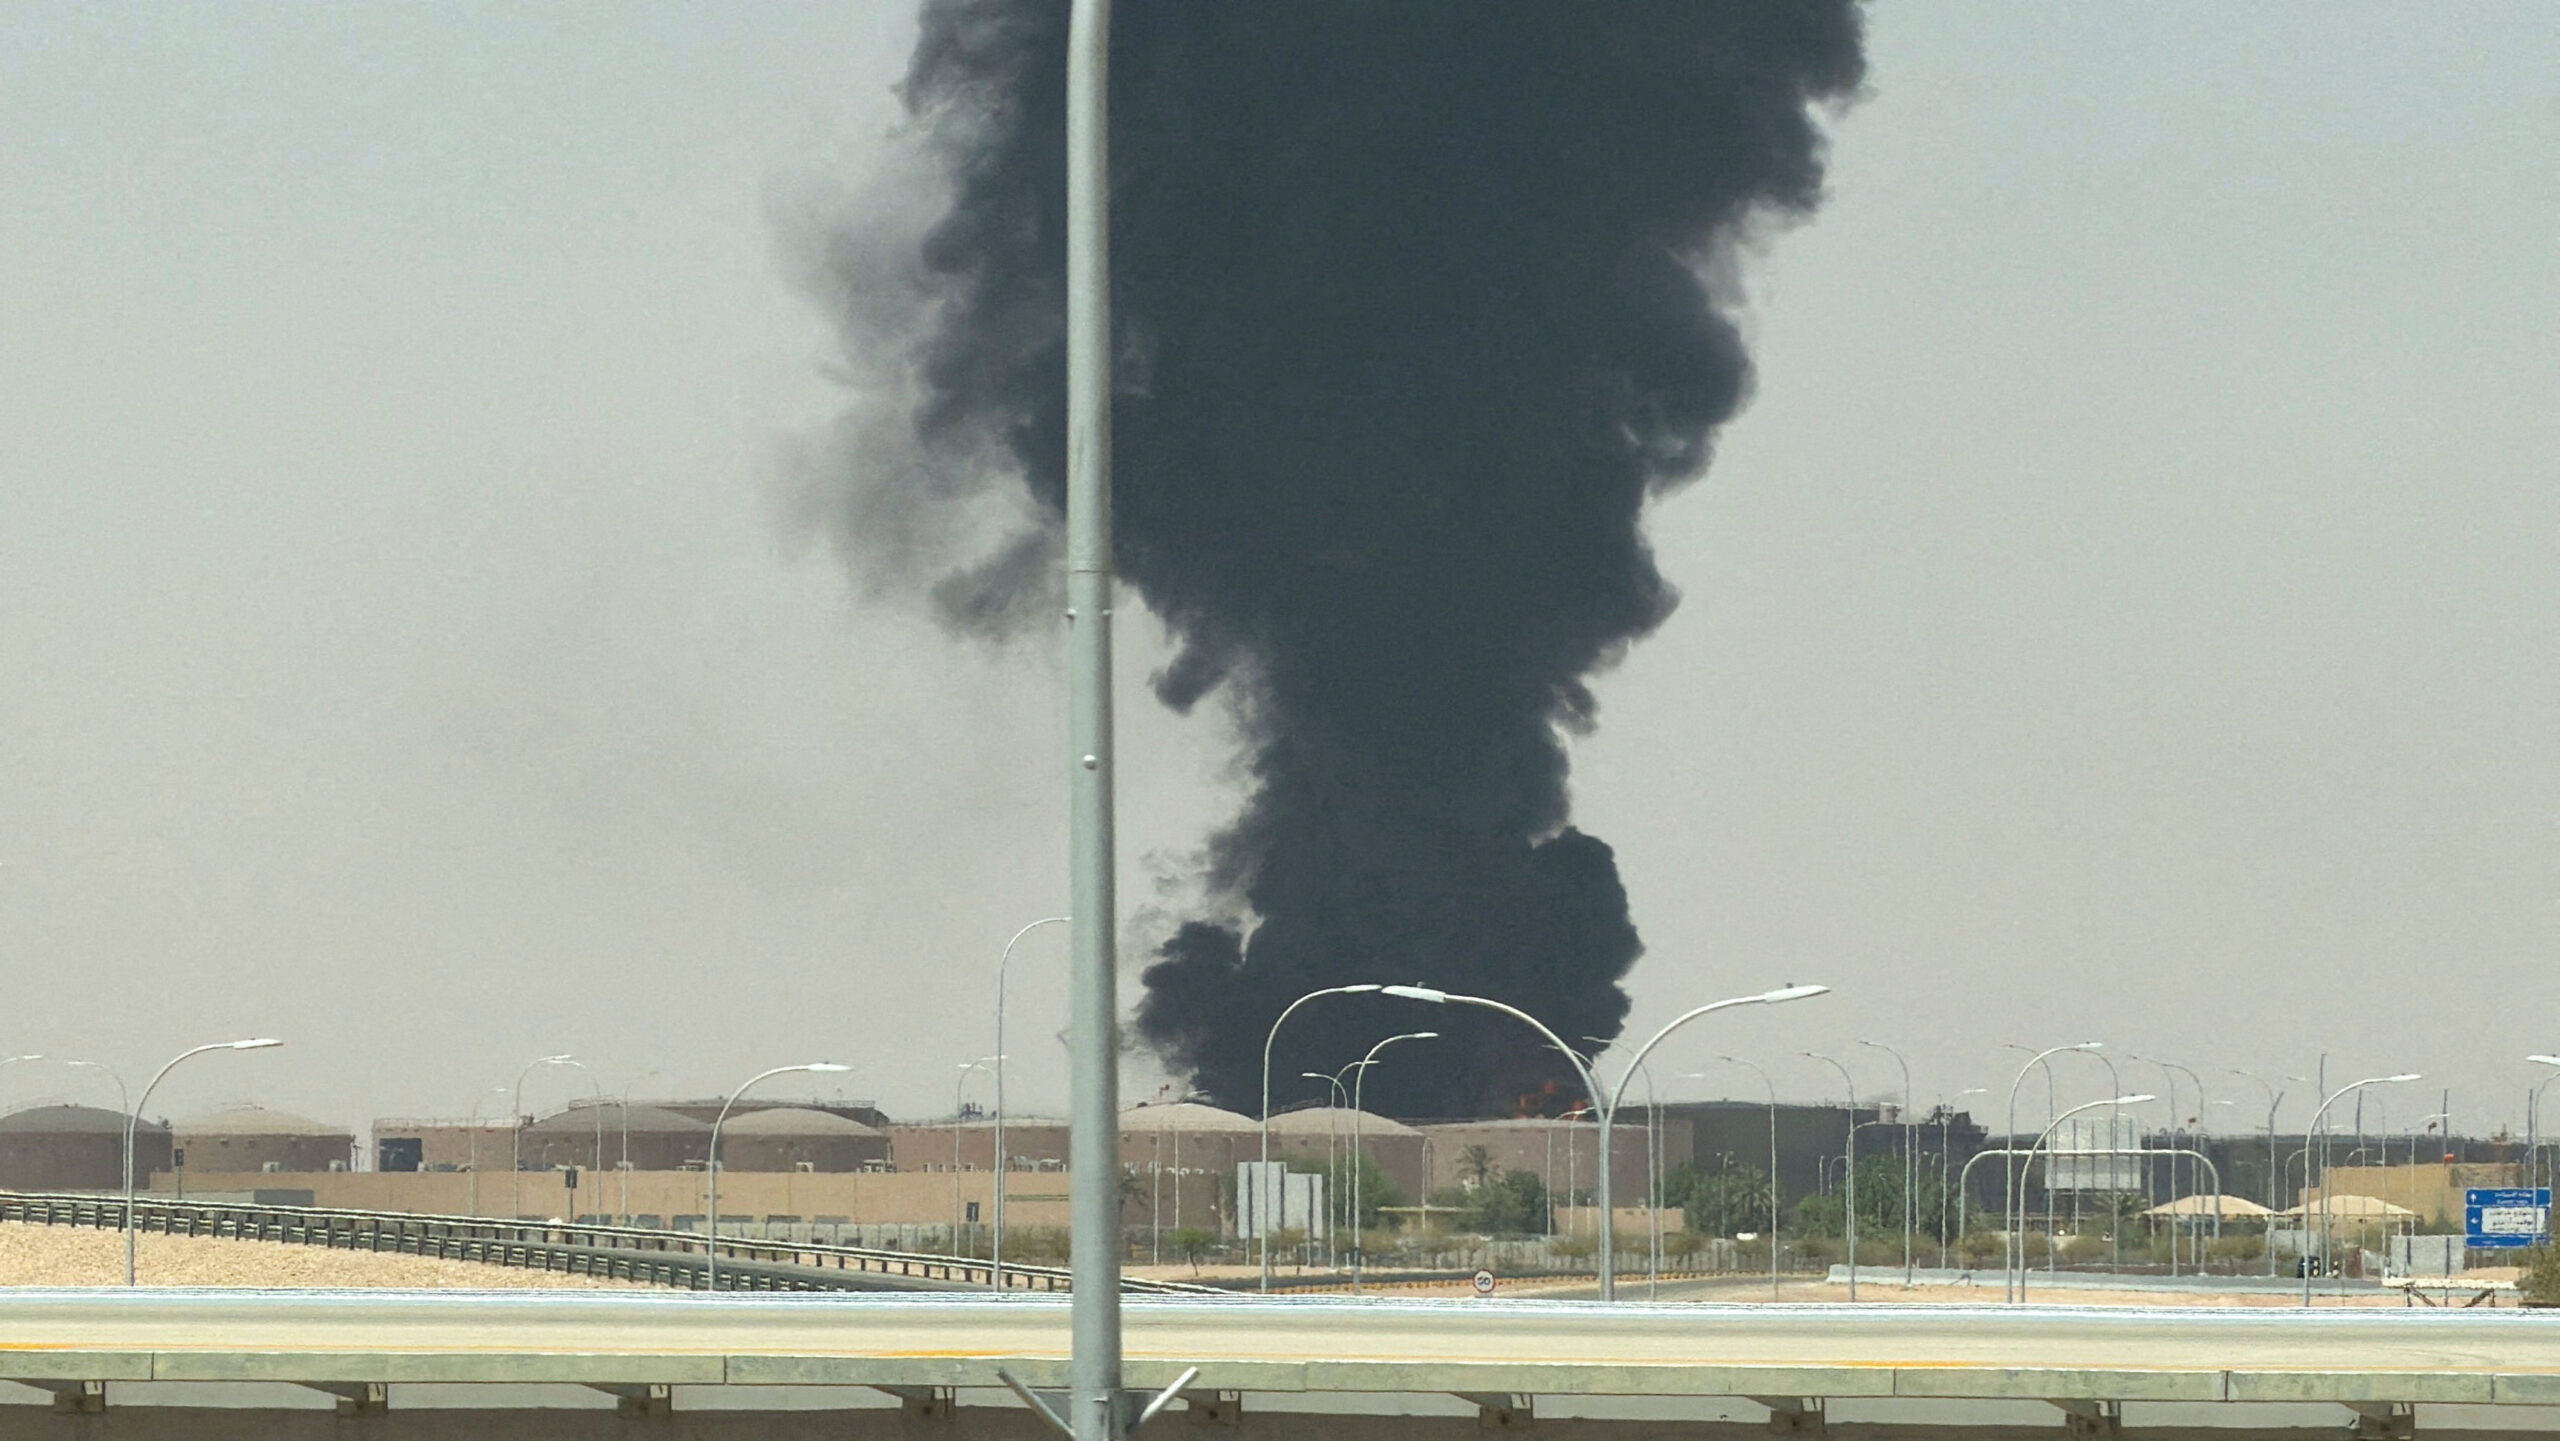
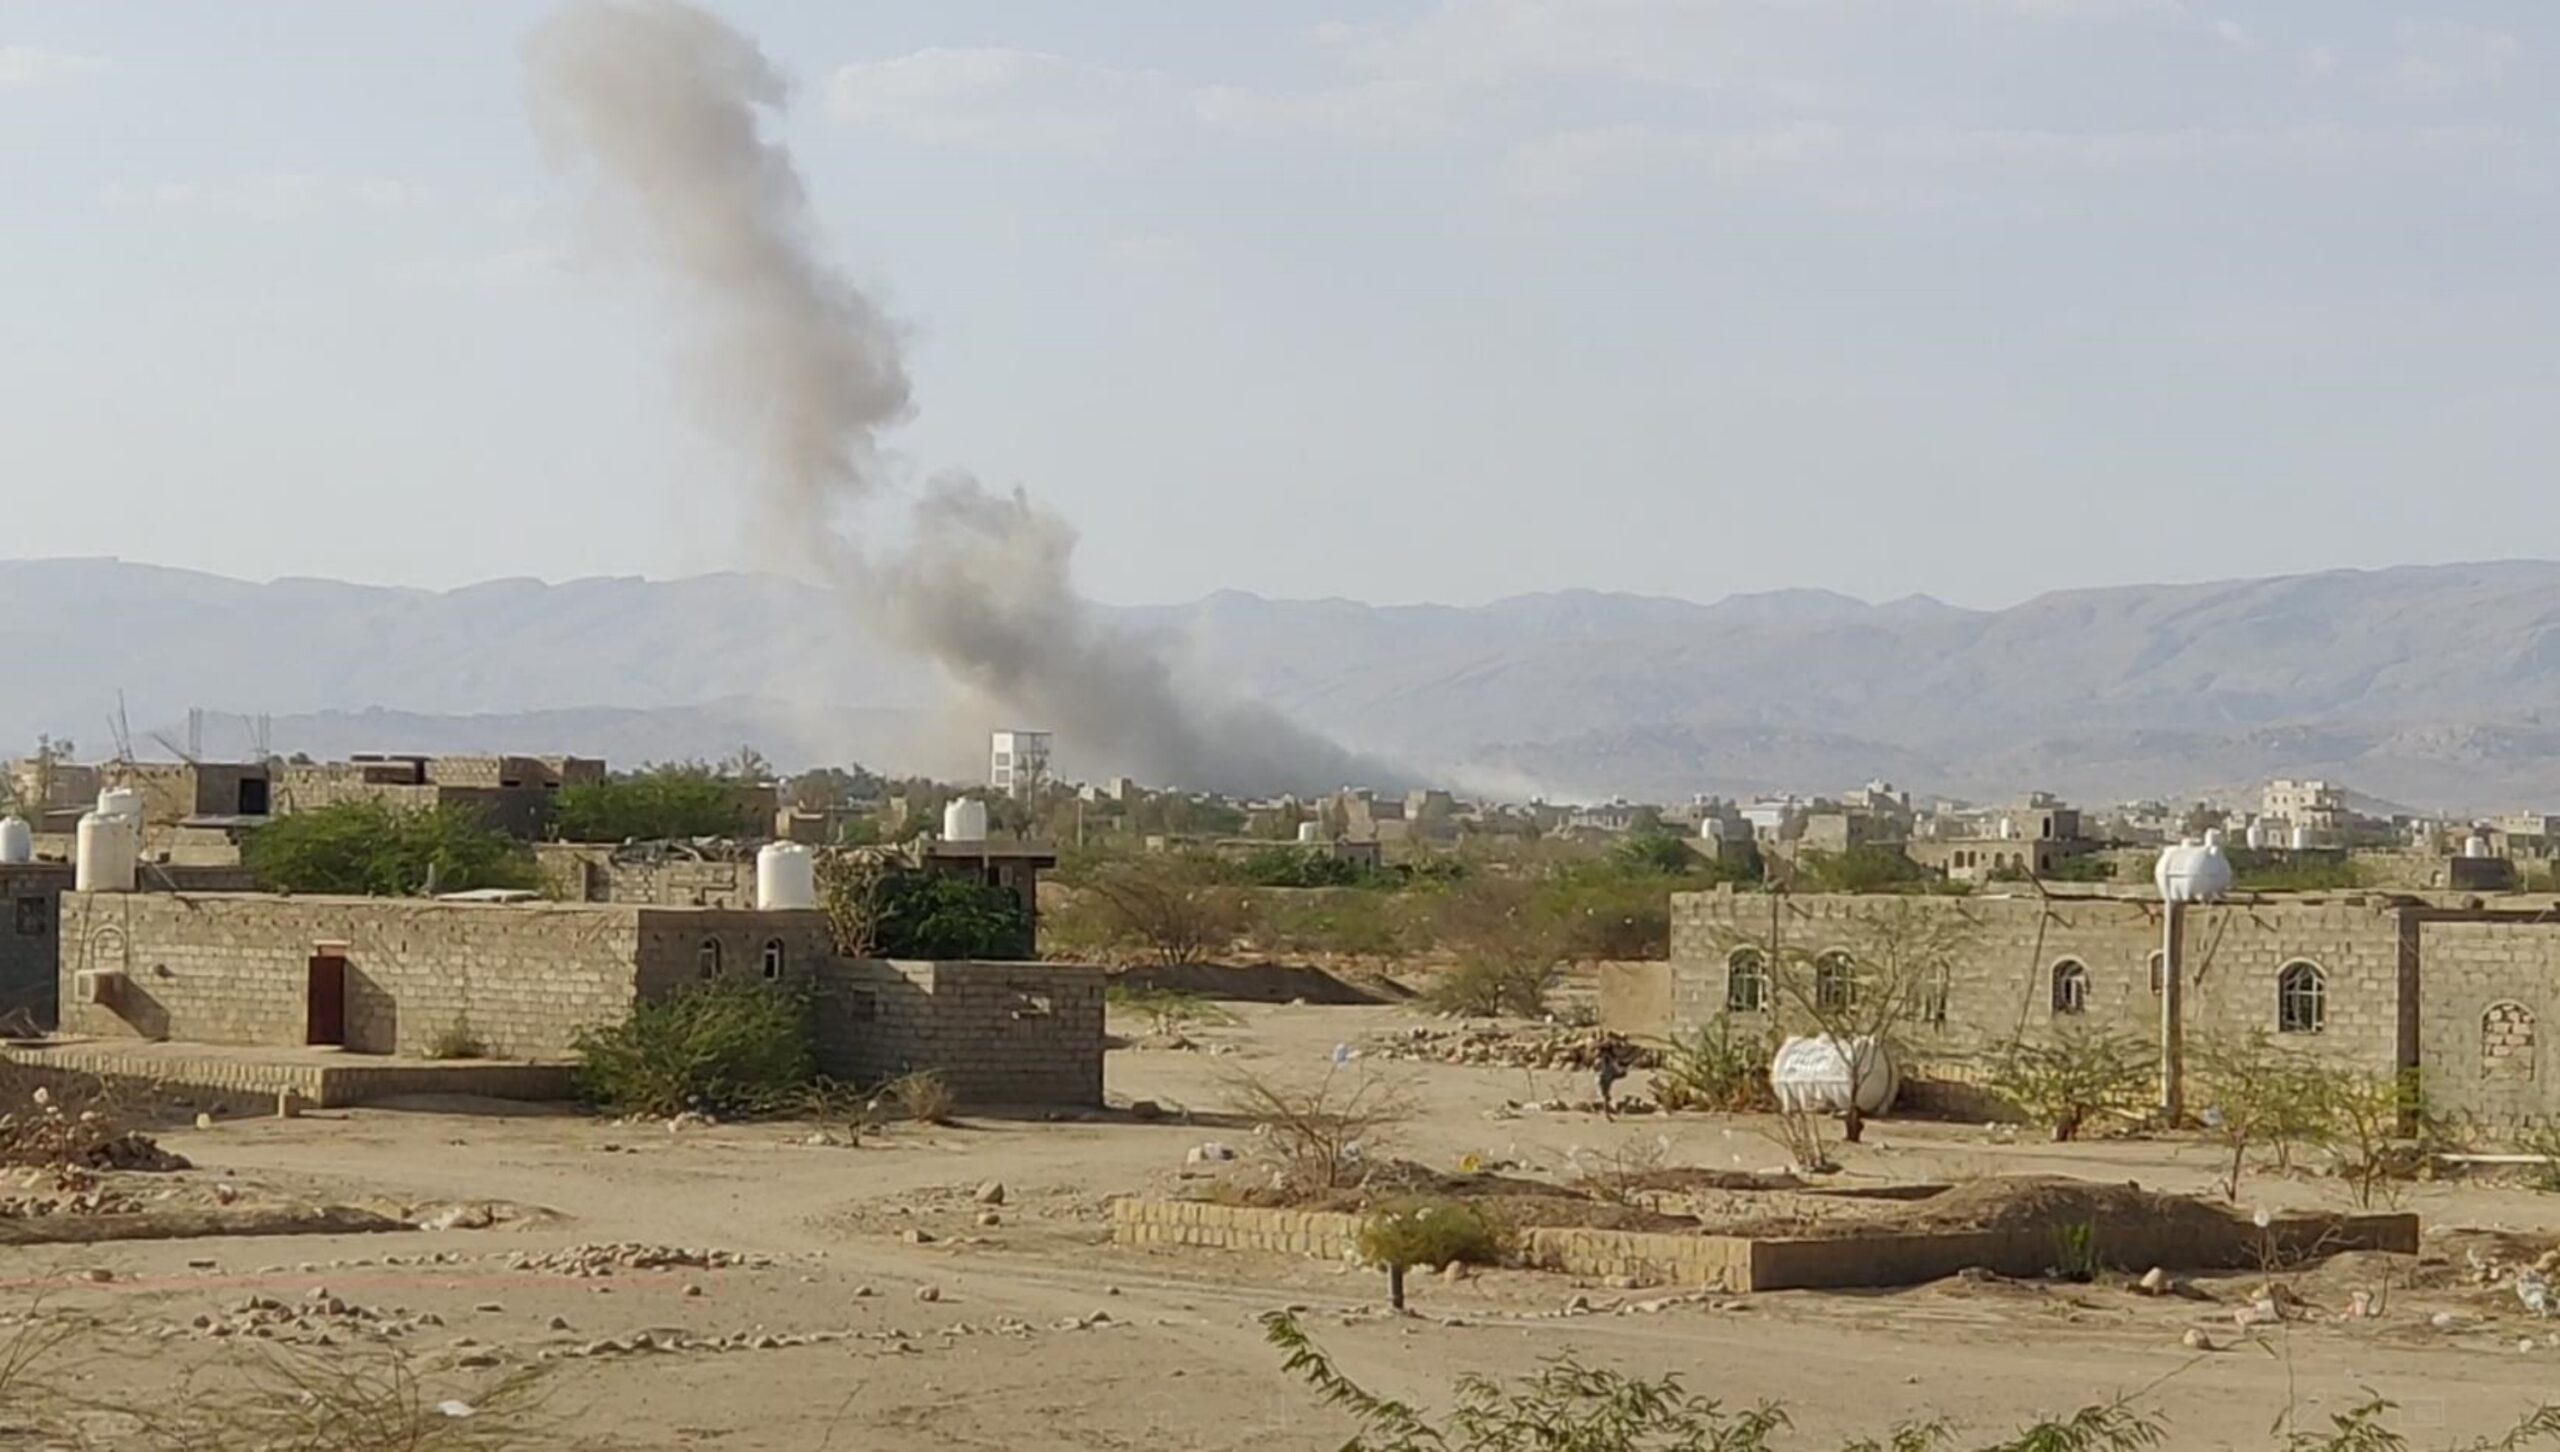
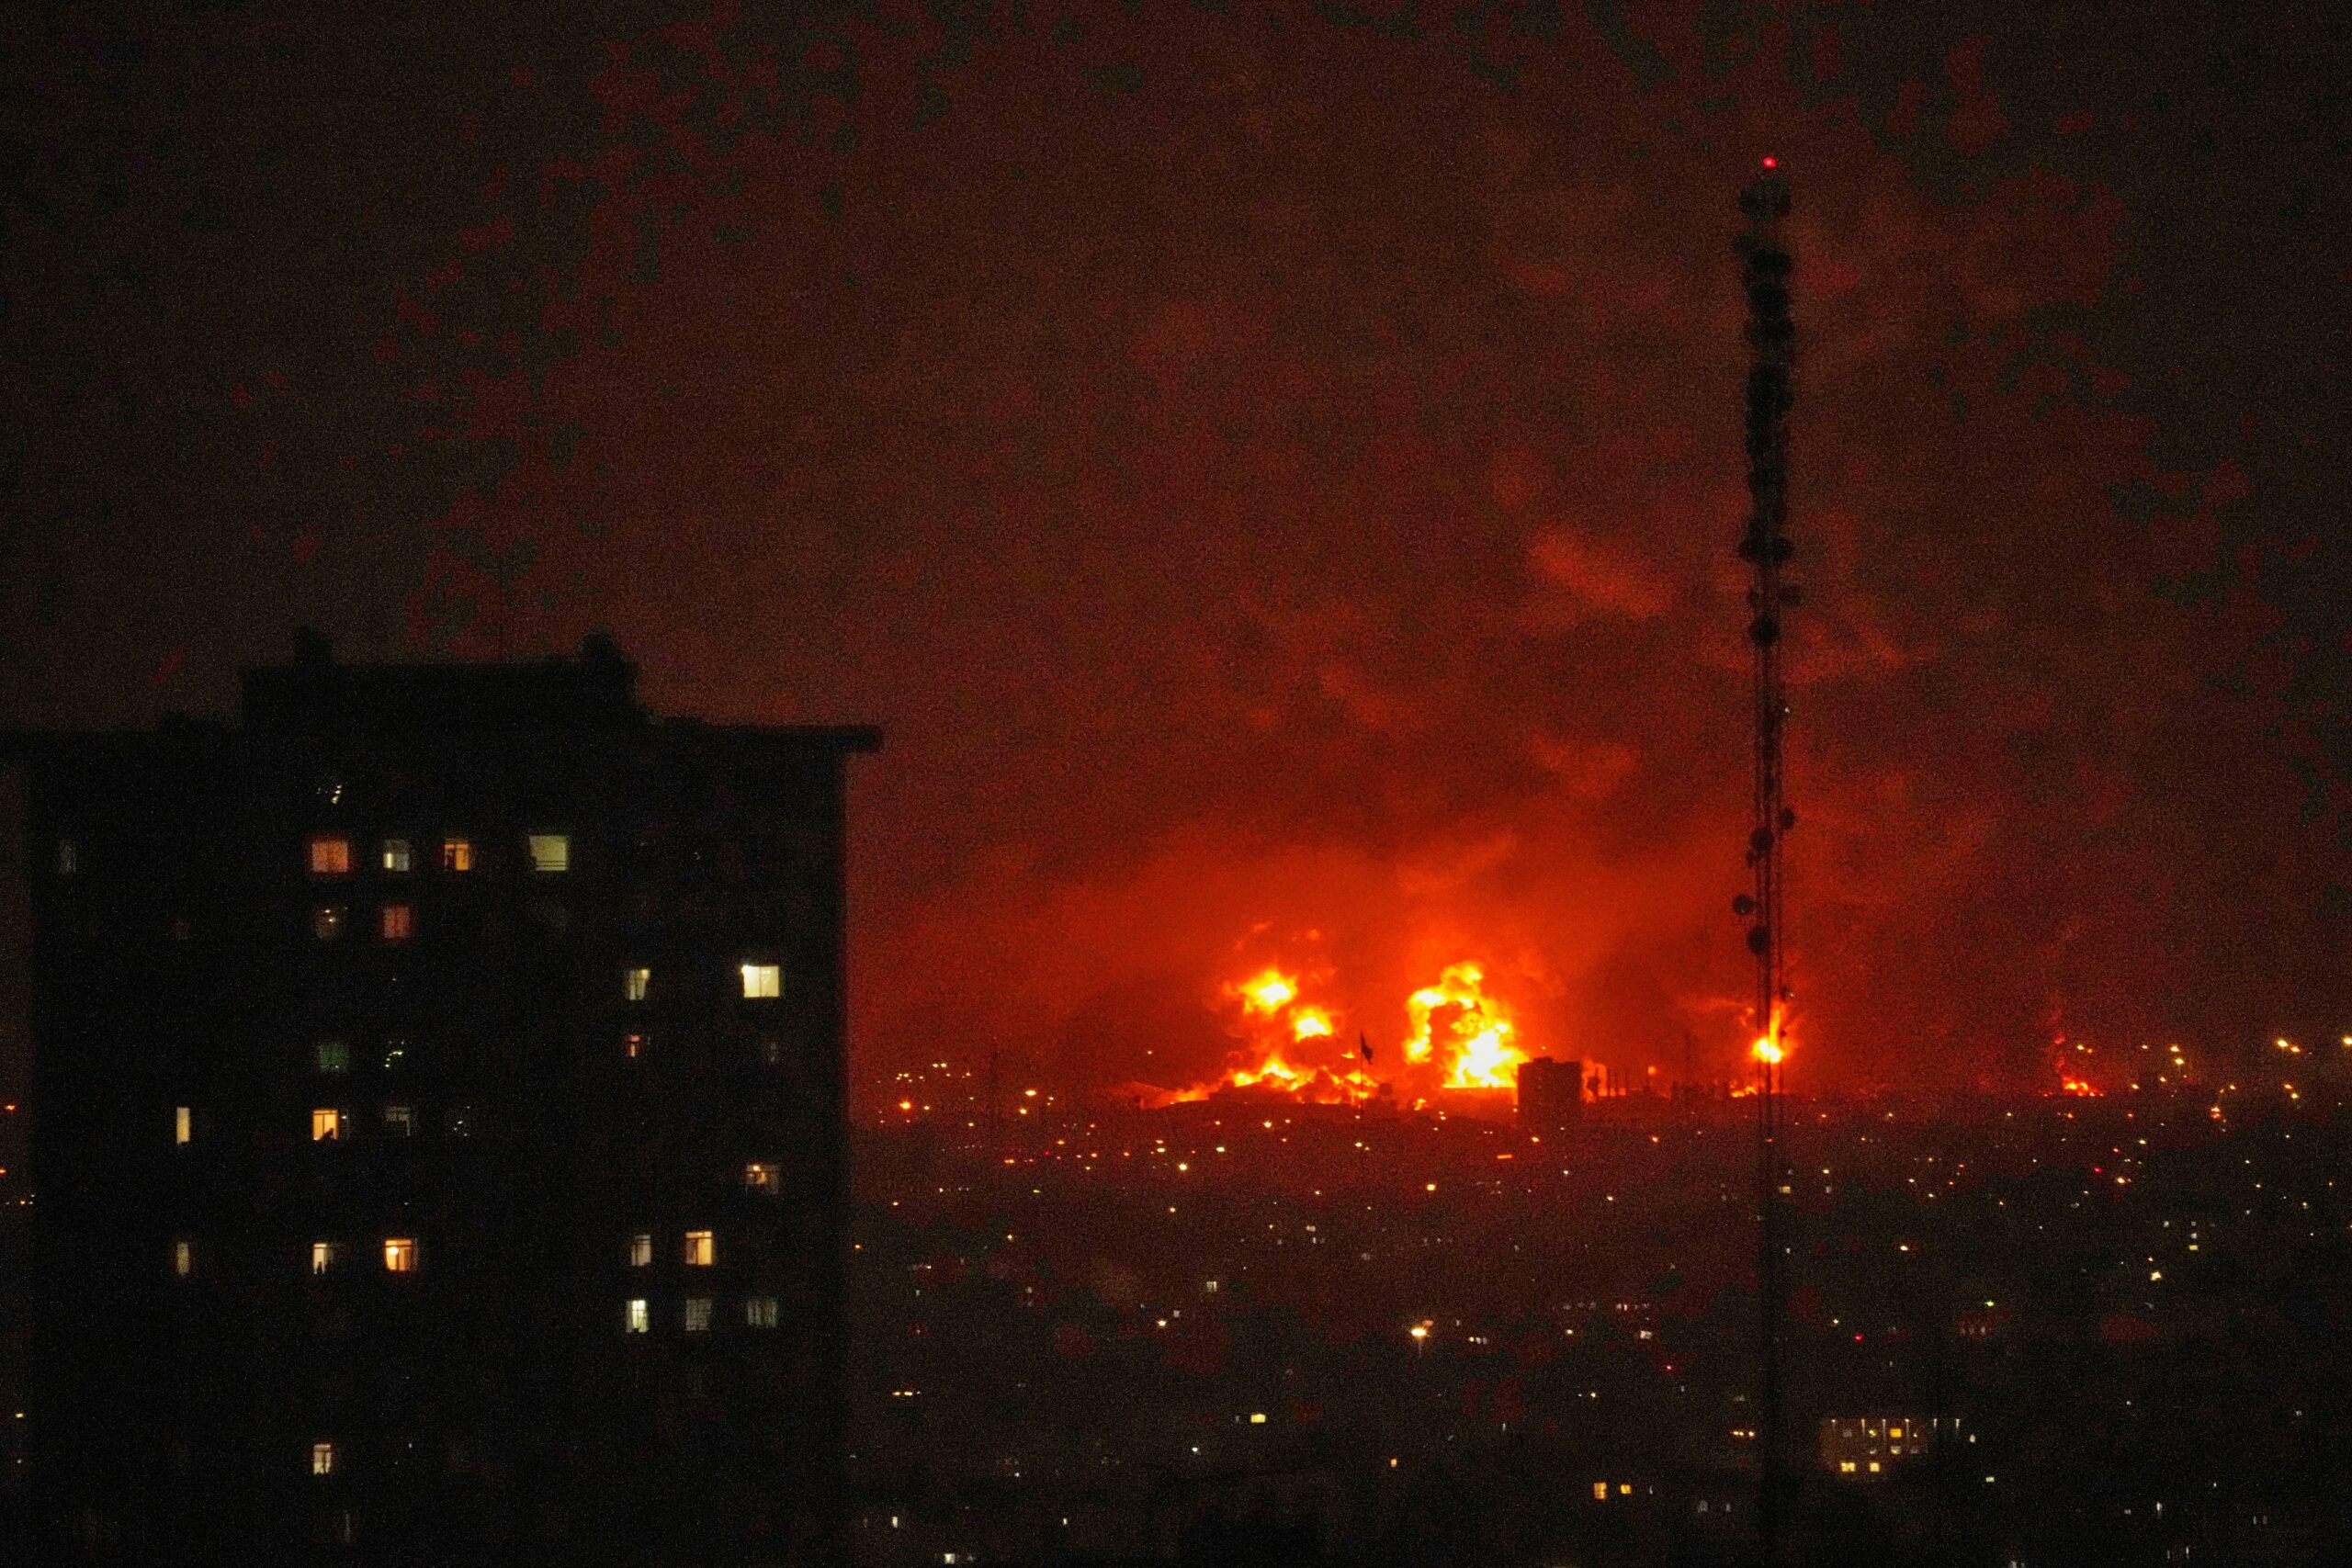
A large plume of black smoke rises from the fuel storage area at King Khalid International Airport, in Riyadh, Saudi Arabia, September 19. (REUTERS/Stringer)
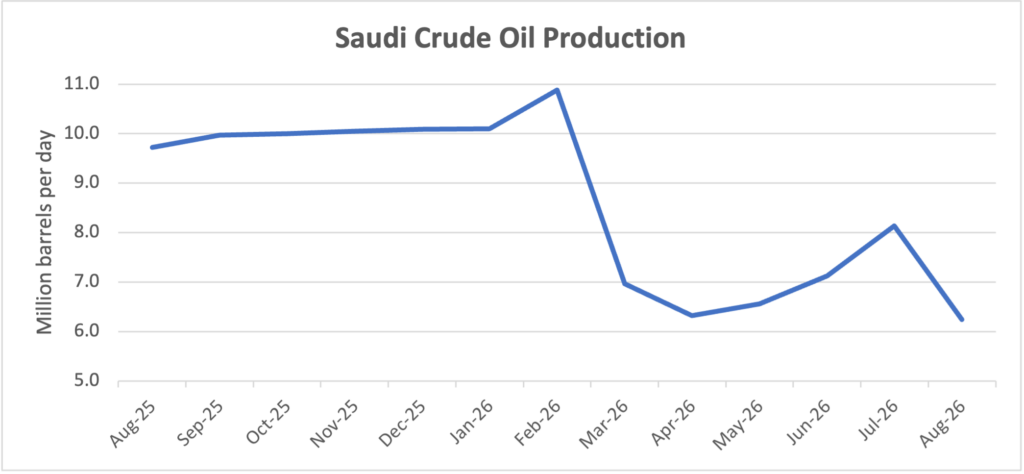
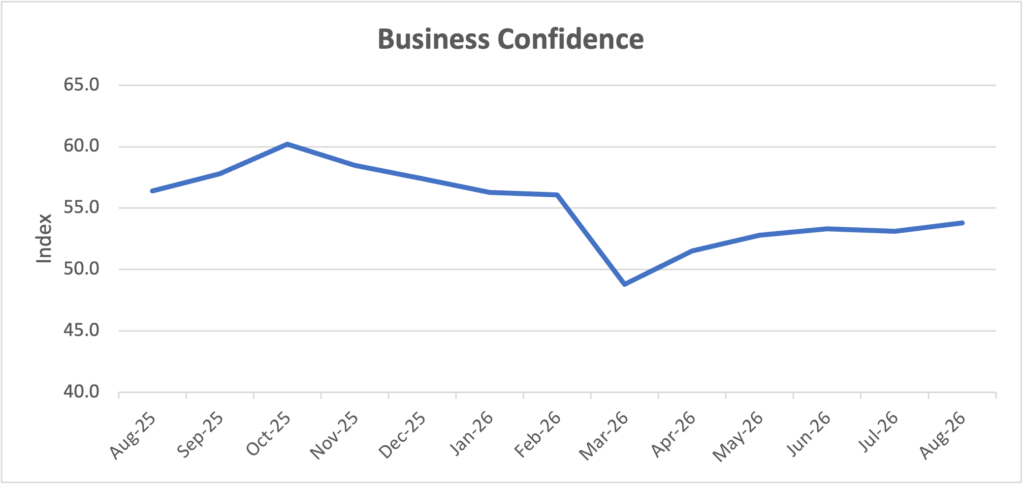
Not long ago, the Saudi economy appeared to be weathering the Iran-U.S.-Israel war relatively well. The East-West oil pipeline had allowed oil exports to continue despite the closure of the Strait of Hormuz, and higher oil prices had compensated for reduced export volumes. In July, oil production had increased to over 8 million barrels per day, its highest level since February. Business and consumer confidence had also risen from March lows, boosting prospects for consumption, investment, and employment. Yes, the economy contracted in the first half of the year, but a strong rebound seemed likely in the second half.
Source: OPEC
Source: Riyadh Bank Note: Business confidence is measured by the Riyadh Bank purchasing managers’ index.
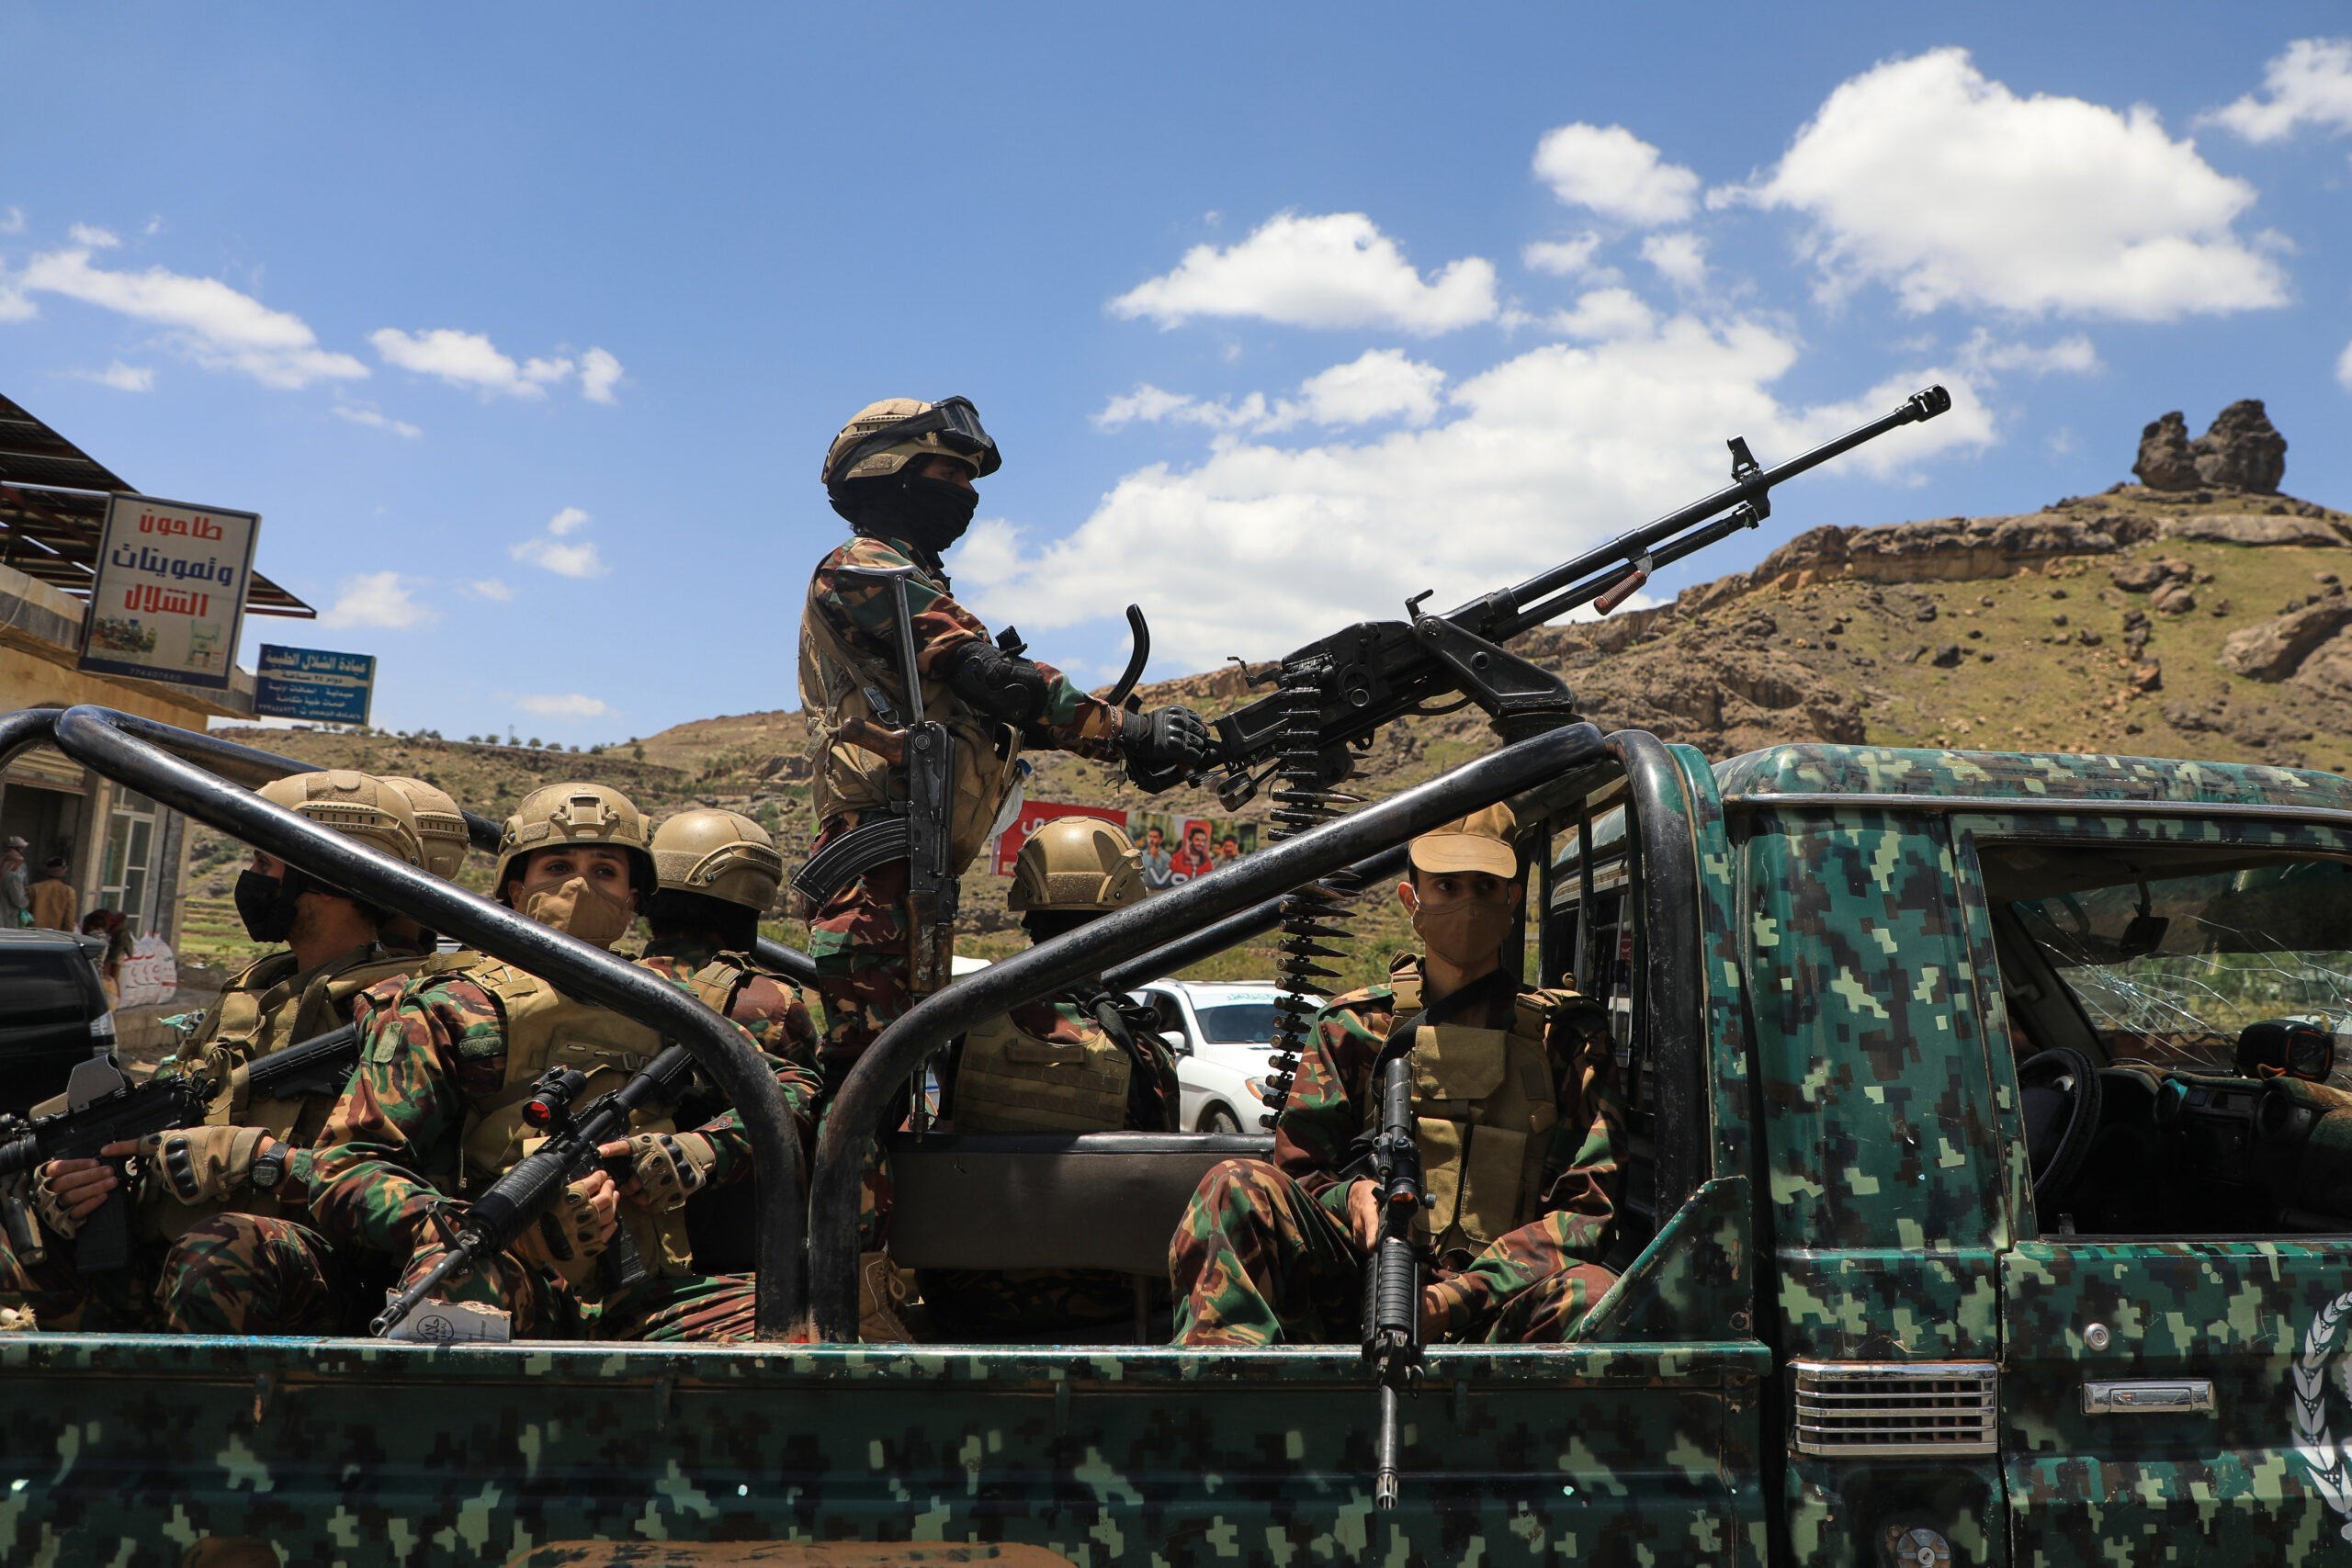
This positive outlook has now changed. New (or renewed) threats to Saudi Arabia have emerged. First, the Houthis announced a maritime embargo on Saudi Arabia on July 20, and attacks on Saudi vessels in the Red Sea followed. Second, the Houthis launched missile and drone attacks on Saudi Arabia, including a recent hit on fuel storage facilities at Riyadh airport. Third, an Iranian-aligned Iraq-based militia attacked the East-West pipeline, inflicting damage that has closed the pipeline.
Economic Growth Weaker Than Previously Forecast
Real gross domestic product is now likely to contract by 6.5% in 2026, a considerably weaker outcome than expected a few of months ago. The main change to the forecast is the more negative outlook for oil production, although non-oil growth will also be weaker than previously thought.
Saudi oil production fell to 6.2 mb/d in August. With the East-West pipeline still closed, oil production in September will likely be lower than in August, although by how much will depend on the ability to redirect oil through the Strait of Hormuz, where U.S. military escorts and ship-to-ship transfers in the Gulf of Oman appear to be supporting some increase in exports. Aramco has not commented on how long it will take to repair the damaged oil pipeline, but third-party reports vary from a few days to 5-6 weeks. Assuming that oil production is around 5 mb/d in September and gradually increases to 8 mb/d by December, real oil GDP would contract by 22% in 2026.
The attacks on Saudi Arabia are likely to dent business and consumer confidence, although this may not be immediately evident in the data. The survey underlying the Riyadh bank purchasing managers’ index, one of the key measures of business confidence, is carried out early in each month. The impact of recent developments on confidence may therefore not be fully apparent until the October survey is published in early November. With a renewed dip in business and consumer confidence likely, real non-oil GDP growth could now be around 1.3% in 2026.
Uncertainty Remains Very High
Uncertainty about the outlook remains very high. The likely duration of the Iran-U.S.-Israel conflict and the Houthi attacks on Saudi Arabia is uncertain, while the impact on oil production from the pipeline closure and disruptions to shipping is still unclear. Recent developments, however, will delay economic recovery and, in a worst-case scenario, could lead to more permanent economic scarring if hostilities continue for an extended period.
The baseline forecast is still for a strong rebound of growth in 2027, but the experience of 2026 shows this should not be taken for granted. What was considered a downside scenario a few months ago has now become the baseline for 2026. The same could happen for 2027 if hostilities continue or escalate further.
While the short-term growth outlook will be determined by the contours of the conflict, what matters for longer-term growth is how the conflict ends and the security situation in the region after. An agreement that significantly reduces the risk of future hostilities should see growth return to its prewar path, as domestic and foreign investors are reassured about the future investment environment. An agreement or nonagreement that leaves regional security issues unresolved and increases the risk of hostilities flaring up again in the future will undermine the investment outlook and keep growth on a lower trajectory than it was on before the war started.
The views represented herein are the author's or speaker's own and do not necessarily reflect the views of AGSI, its staff, or its board of directors.
Saudi Arabia’s ability to maintain its reputation as a reliable supplier in the months ahead will depend on how quickly it can repair damaged assets and keep several imperfect routes operating at the same time.
In tandem with President Trump’s refusal to offer help with the Houthis, the Saudis are facing grim options to reverse Houthi military successes and a chokehold over their oil exports.
The outbreak of the Iran war has halted the deepening of the economic relationship between the United States and the Gulf countries. While likely temporary, it could take some time before the upward trajectory is restored.
The impact of the Iran war on the Saudi economy has been mitigated by investments in “economic resiliency,” including the East-West oil pipeline, relatively prudent fiscal policy, and the accumulation of a large stock of foreign financial assets.
If the memorandum of understanding between the United States and Iran holds, the Saudi economy will grow strongly in the second half of 2026 and into 2027.
On January 8, AGSI hosted a virtual roundtable with its leadership and scholars as they look ahead and assess trends likely to shape the Gulf region and U.S. foreign policy during the coming year.